All Top Banking

The First Credit Cards - A Quick History

Posted by John B. Frank Tuesday, September 23, 2008 0 comments

Found this article in iafrica.com and thought it interesting. I especially got a kick out of Henry Fonda's Texaco Credit Card from 1953 pictured on the right.

iafrica.com |The history of credit
The History of Credit

Article by FNB and VISA

To know where you are going, it is important to know where you have been. With the increasing use and acceptance of plastic money in the form of debit, credit and pre-paid cards, as well as the growing global movement towards a cashless society, we investigate the history of the card and offer insights into where the industry is heading.

Credit was first used in Assyria, Babylon and Egypt 3000 years ago. The bill of exchange — the forerunner of banknotes — was established in the 14th century. Debts were settled by one-third cash and two-thirds bill of exchange. Paper money followed only in the 17th century.

Christopher Thornton, offering furniture that could be paid off on a weekly basis, placed the first advertisement for credit in 1730. From the 18th century until the early part of the 20th, tallymen sold clothes in return for small weekly payments. They were called 'tallymen' because they kept a record or tally of what people had bought on a wooden stick. One side of the stick was marked with notches to represent the amount of debt and the other side was a record of payments. In the 1920s, a shopper's plate — a 'buy now, pay later' system — was introduced in the USA. It could only be used in the shops that issued it.

The first charge cards

In 1950, the first 'plastic money' — charge cards — were issued in the USA, followed in the next year by the arrival of the first-ever credit cards issued to 200 consumers who could use them at 27 restaurants in New York. But it was only until the establishment of standards for the magnetic strip in 1970 that the credit card became part of the information age.

Since the introduction of bank cards in the early 1950s, the global acceptance and use of this form of payment system has grown exponentially. Today there is even a word for the study of money-like objects, such as credit cards, namely exonumia.

Exonumiasts collect any form of money — from the now familiar plastic cards to older paper merchant cards and even metal tokens that were accepted as early merchant credit cards. The first credit cards were made of celluloid and then metal and fibre, then paper and are now plastic.

Within the first seven years 5-million credit cards circulated in the US

Payment cards are a relatively recent development. Visa, for example, traces its history back 50 years to 1958 and within the first seven years 5-million credit cards circulated in the US.

Long before the first credit cards were issued, a visionary of the 19th century wrote that a cashless society, using credit cards for purchases, would exist at the end of the 20th century. Falling asleep in 1887, the narrator of Edward Bellamy's novel Looking Backward, published in 1888, wakes in the year 2000 to an America whose problems have been solved by getting rid of buying and selling.

Instead, 'A credit corresponding to his share of the annual product of the nation is given to every citizen on the public books at the beginning of each year, and a credit card issued him with which he procures at the public storehouses, found in every community, whatever he desires, whenever he desires it.' Bellamy's credit card is actually more similar to what we would call a debit card — one that draws from an established account.

The credit card was the successor of a variety of merchant credit schemes following the development of store-specific metal charge cards in 1928. These cards continued the system of extending credit to favoured customers and in 1938 several companies in America started to accept each other’s cards.

Early charge cards did not possess the key feature of modern credit cards: revolving credit, which allows cardholders to pay balances over time, while simultaneously charging new amounts. There are now countless variations on the basic concept of revolving credit for individuals, including organisation-branded credit cards, corporate-user credit cards and store cards.

The growth of credit cards has had an enormous impact on the global economy

The growth of credit cards has had an enormous impact on the global economy, changing buying habits by making it much easier for consumers to finance purchases.

Advances in technology have facilitated the use of credit cards. Merchants are now connected to banks electronically, so purchases are approved rapidly; online shopping on the Internet is possible with payment cards.

An alternative to credit cards is the debit card, which deducts the price of goods and services directly from customers' bank accounts. The design of the card itself has become a major selling point in recent years. Since the value of the card to the issuer is related to the customer's use of the card, there has been a rise of co-brand and affinity cards, leading to higher card use. In most cases, a percentage of the value of the card is returned to the affinity group.

The introduction of the latest in Visa chip card and contactless technology is bringing about the next evolution in plastic cards. Transactions are not only easier and more convenient, but may feature increased security as the card never leaves the holder's hand. Editor's Note: I don't know about that statement. RFID, by some accounts, may have a major security flaw enabling fraudsters to intercept the wireless transmission of the radio frequency waves. Doesn't have to leave the pocket. I've read reports that indicate the card information can, ironically, be "swiped" while it's sitting in the consumers wallet.

This cutting edge technology has an application beyond just banking and the functionality chip cards offer holds much potential for the card industry. The amount of storage space and the processing power of the chip card may allow various forms of information to be stored and utilised, such as biometric and personal contact info. These advances may likely contribute to making the concept of a cashless society a reality and also make the idea of having a single card for everything you need a realistic possibility.

While we still have some way to go before reaching Bellamy's vision of a cashless society, the rise of plastic money has put payment cards in nearly everyone's hands and it certainly looks to be a pivotal mechanism in the future of payment.
Reblog this post [with Zemanta]

September 23, 2008 by Gill Montia

Story link:
Cardholders flock to secure online payment methods

UK payment services association, Apacs, has reported a major increase in the volume of credit and debit card holders taking advantage of measures that can prevent online shopping fraud.

According to Apacs, over 25 million cards are now registered with secure online payment systems, Verified by Visa and MasterCard SecureCode. Cardholder registration in August was up 150% over the year and had increased by nearly 600% on August 2006. The process of signing up is simple and can be completed on the websites of card providers.

The schemes offer enhanced protection against the unauthorised use of a card and provide state of the art online security without the need for additional software.

Online shopping card fraud was estimated at £223.8 million in 2007, when it formed around 77% of total card-not-present fraud losses in the UK. Last year’s figure was up from 45% from 2006, when Internet fraud losses stood at £154.5 million and accounted for 73% of total card-not-present fraud losses.
Reblog this post [with Zemanta]

Visa today announced that it will begin supporting the issuance of "unembossed" cards in the U.S. for Visa consumer debit, business debit and consumer credit cards. Unembossed payment cards feature printed personalized information, such as the account number and cardholder name, rather than embossed with raised lettering currently found on most U.S credit and debit products.

By changing the Visa U.S.A Inc. Operating Regulations to allow the issuance of unembossed cards, Visa is providing more choice, flexibility and value for issuers and their cardholders. The move follows a series of successful pilot tests with a dozen U.S. financial institutions, including Commerce Bancshares, Inc., TD Banknorth and United Heritage Credit Union.

"Being able to instantly provide members with Visa cards has helped us drive activation, usage and loyalty while reducing costs," said Michael Ver Schuur, executive vice president at United Heritage Credit Union, which participated in a pilot program testing the unembossed Visa cards. "Not only that, our cardholders felt secure receiving their cards directly at the branch and enjoyed the ability to access their accounts conveniently right away."

Traditional embossed cards typically require lengthier production times and more complex supply chain management. Because the cards have to be created offsite, they are generally shipped to the cardholders days after enrollment, leaving the new cardholder unable to make purchases or conveniently access cash at ATMs in the interim or relying on a temporary generic card. The ability to provide personalized printed cards instantly at the bank branch enables cardholders to take advantage of their cards immediately.

Visa has permitted unembossed prepaid cards in the U.S. since 2005. The new regulations give issuers the ability to also issue a consumer debit or credit card as well as a business debit card immediately to customers, giving them greater flexibility to manage their Visa card distribution methods to best fit their business needs."Visa is always looking for ways to bring more value to our clients and their cardholders," said Stacey Pinkerd, Head of Global Consumer Debit Products, Visa Inc. "By allowing the issuance of unembossed cards, we enable issuers to choose the distribution method that best meets their business needs, while offering customers greater flexibility and customization. Looking ahead, we will continue to innovate to provide products that meet financial institutions' demand for flexibility and cardholders' demand for convenience and security."

Visa unembossed cards are accepted by most Visa merchants, with the exception of those who require a manual imprint at the point of sale such as with an old-style "zip-zap" machine, and can be used for purchases made online, by mail or by phone.


Reblog this post [with Zemanta]

More on the Tealeaf/Harris Interactive e-Commerce Poll

Posted by John B. Frank Monday, September 22, 2008 0 comments

Intolerance for online transaction issues jumps among British consumers in 2008

Survey highlights £11.9 billion revenue opportunity for GB businesses that focus on improving online customer experiences.
An independent annual survey into online consumer behaviour conducted by Harris Interactive, and commissioned by Tealeaf highlights an increasingly unforgiving attitude towards online sites.

The study reveals that nearly 9 out of 10 British online adults (89%) who have conducted transactions online in the past year have experienced problems. Of those who have experienced problems, nearly half (49%) say they would abandon their transaction entirely or switch to a competitor (either online or offline) if they experienced a problem, a significant increase of 12 percentage points in just one year (37% in 2007). The 2008 rate of abandonment suggests that £11.9 billion in revenue could be affected by issues on shopping sites alone -- a huge opportunity for companies to harness, by ensuring their websites work. On the Web, the competition is a click away.

The ecommerce sector is buoyant in the UK, with shoppers spending over £26.5bn online in the first six months of 2008 (up 38% on 2007). Remarkably, the Tealeaf survey also found that, among all online adults in Great Britain, general preference for conducting business online (52%) has surpassed preference for conducting business in-person (41%) by more than 10 percentage points.

Simultaneously, expectations for online experience are also high. A full 87% of all online adults believe there is no reason why an online transaction cannot be completed first time, and 90% of those who have conducted an online transaction in the past year expect the same, or better, levels of customer service online as they do offline.

In addition to losing customers to the competition, companies that fail to provide high levels of online customer experience will likely see their reputation suffer as a result. Online transactional problems may lead to negative feelings towards companies -- 83% of online adults who experience problems conducting online transactions say they feel frustrated when they experience problems. The effect of this can be far-reaching, with 77% sharing their experience with others and with more than half (53%) telling their friends and family specifically in order to discourage them from using that website or doing business with the company. Of those sharing their experiences, 56% use online channels to share complaints or reviews. Unlike one-on-one conversations with friends or family, these digital conversations can be viewed by millions and live online indefinitely, therefore amplifying their impact.
Reblog this post [with Zemanta]

Skim Scam

Posted by John B. Frank 0 comments


The Calgary Sun - New debit scam caught on video
They're a scourge to society and nefarious PIN pad peekers are nothing if not inventive.

A surveillance video recently obtained from an Airdrie convenience store shows a startling debit fraud scam far more sophisticated than so-called "shoulder surfing" and skimming machines, prompting the RCMP to warn retailers and customers alike.

"We're in a constant race, along with the banks and the financial institutes, to defeat what they're doing next ... this is an advancement for the criminals," Sgt. Patrick Webb said yesterday.

The footage, dated Sept. 11, shows three men entering the store just before closing time -- two acting as lookouts and distracting the clerk, the other covertly inspecting the business' PIN pad.

A fourth suspect, a woman, enters and uses a bag to shield the PIN pad from the retailer's view -- and ultimately, the man at the counter swipes the store's device and replaces it with a dummy pad.


It's a scheme likely to give crooks access to information from dozens of debit cards from a single retail location in just one day, said Const. Lane Menard of the RCMP's commercial crime section.

"Now that they've taken this pad, they go to a separate location, open it up and place some technology inside that allows them to copy the information from swiping your card, as well as a transmitter where they can receive all that information," said Menard.

"They will return the next morning with that original PIN pad, take their covert one and everything functions, and we're none the wiser."

In the case captured on video, a customer visited the store shortly after the card-swiping quartet departed and, when the debit pad didn't work, the retailer promptly notified authorities.

Mounties determined the dummy pad was actually stolen from Surrey, B.C., merely a day before.

In 2006, 119,000 debit cards in Canada had information lifted -- a small percentage considering the millions in circulation.

But, Menard said store owners should secure their PIN pads or keep them out of reach, while consumers should check their accounts for any
Reblog this post [with Zemanta]

PaymentsSource Webinar Available for Public Viewing

Posted by John B. Frank Friday, September 19, 2008 0 comments

Last week I posted "PaymentsSource Webinar Review" about attending a webinar on a new online publication coming out from SourceMedia they call "PaymentsSource."

SourceMedia publishes American Banker, Bank Technology News, ATM & Debit Card news and more.

If you would like to view a replay of the webinar you can click below:

take me to the replay now

Reblog this post [with Zemanta]

eMarketer reports that the John Lewis Group, UK's leading store group saw online sales grow at a 30% clip while the groups department store physical locations saw a 34% drop in operating profit...


Top UK Retailer Pins Hopes on Web - eMarketer
Top UK Retailer Pins Hopes on Web
SEPTEMBER 19, 2008

Karin von Abrams, Senior Analyst

On September 11, John Lewis, the leading UK store group, announced a 27% fall in pretax profits for the first half of 2008.

Earlier this year, the company said it hoped to avoid the worst effects of the impending recession thanks to its loyal customer base, the opening of several new stores and significant diversification into Internet selling.

That hope in Internet sales may be well-placed. Retail e-commerce sales in the UK are predicted to reach £44.9 billion ($80.8 billion) in 2012, up from £19.5 billion ($38 billion) in 2008, according to Verdict Research data cited in Internet Retailing.

UK Retail E-Commerce Sales, 2002-2012 (billions of £ and % of total retail sales)

eMarketer estimates that B2C e-commerce in the UK will reach £94.2 billion ($169.6 billion) in 2012, up from £59.8 billion ($116.6 billion) in 2008.

Verdict's figures are significantly lower than eMarketer's because Verdict excludes air travel and tickets from its estimates, whereas eMarketer includes them. Verdict also gathers data from UK adults only, while eMarketer estimates include online sales to UK residents ages 14 and older.

The John Lewis group, owned as a cooperative by its employees, made pretax profits of £108 million ($191 million) in the six months to July 26, 2008, said a spokesman. Sales overall rose 3.6% to reach £3.27 billion ($6.38 billion).

The company's physical stores are bearing the brunt of the economic storm.

Operating profit at the group's department stores was down 34%, and at its Waitrose supermarkets—considered pricier for consumers than other major grocery chains—operating profit fell 8%. Price cuts and promotions, designed to appeal to worried shoppers, accounted for much of this loss.

But the group's Internet ventures continued their recent robust performance, strengthening hopes that online shopping will help John Lewis come through the current downturn in good shape. During the first half of 2008, online sales rose a healthy 30%.
Reblog this post [with Zemanta]

SiliconRepublic.com: Irish retailers are selling €12m a day online - Business

Irish businesses are now selling up to €12m in goods and services online every day, an e-commerce strategist has claimed.

Ennis-based e-commerce strategy company Magico.ie said that while traditional retailers are facing a downturn, online retailing is on track to break new records.

Paul McGurran, director of e-commerce at Magico.ie, said that despite the current economic climate, “online retailing” is still very much in growth mode compared to traditional high-street retail activity.

“Although traditional high-street retail activity is suffering a downturn, internet sales in Ireland are likely to smash all previous records this year as more and more drop the high street for the information super-highway.

“For example, according to Realex Payments, peak online sales in Ireland reached €12.7m on 4 December 2007 last year, declining to €7.3m in subsequent days during the Christmas period. In 2008, average daily web sales in Ireland are now exceeding €12m per day’.

McGurran pointed to recent research in the UK showing that internet sales will continue to grow and the web channel will claim more than half of the retail market pie by 2026.

“This increase in online retail activity is being stimulated by numerous factors, including greater broadband penetration across Ireland and time-poor and price-conscious consumers.

“Furthermore, the rising price of fuel is the main reason behind consumers’ inclination towards web shopping, with users spending an average of 1.6 hours each week buying on the internet,” McGurran added.

Magico.ie was established in 1999 and currently employs 13 people at its headquarters in Ennis, Co Clare. Its current client base includes Fujipix.ie, The Bag Shop, Smyths Toys, Irish Auctioneers & Valuers Institute, Evergreen Healthfood, Munster Rugby Supporters Club, Freshways Sandwiches, Sisk Builders and Fitzpatrick Design Hotels.

The Magico.ie team consists of industry experts who have worked on large Irish and overseas ICT projects with partners such as IBM, Microsoft, Tesco.com, Ireland Online, Bank of Ireland Asset Management and many more.

Retailers wishing to develop an ecommerce Strategy are being invited to attend an e-commerce Seminar from 7-9pm at The Morgan Hotel, Templebar, Dublin on 15 October 2008. For more information go to www.magico.ie

By John Kennedy
Reblog this post [with Zemanta]

2B or not 2B? That be "B2B" says American Express.

Posted by John B. Frank Thursday, September 18, 2008 0 comments

American Express Views B2B Model as Lower Risk, Higher Returns than Consumer Segment

From an article posted on Commercial Payments International.com the global resource for commercial cards and payments professionals. To subscribe to their weekly newsletter, click here or the graphic to the right.

American Express emphasized its growth and opportunities in the B2B segment at a recent investor presentation. It stated that the B2B model has lower risk, higher returns, higher growth and is more geographically diverse than the consumer model. This was proven by a review of recent results posted by American Express.

In Q2 08 the B2B businesses of American Express generated 31% of its net revenues but delivered 55% of its net income. For all of 2007 these numbers were 29% and 38% respectively.

Source: American Express


The global commercial card product alone billed $122 billion in spend last year across 36 markets. The B2B model also has less of a dependence on the US market, generating 55% of its revenue from this developed market vs. 75% for the consumer segment. In difficult economic times as the US is now experiencing fluctuations in the B2B business will not impact American Express' results as much as those on the consumer side.

Other key indicators, such as ROC and ROE are also more rewarding from the B2B business. For one year the segment ROC was 48% for global B2B against 33% for global consumer. In Q2 08 this showed even a larger disparity with B2B still at 48% compared to 22% for consumer. ROE for the most recent year was 44% for global B2B and half of that, or 22%, for global consumer.

CAGR for the global B2B business was 11% from 2005 – 2007. Specific segments are delivering more of this growth with the corporate card middle market growth above or close to 20% since 2004.


American Express is concentrating on three main strategies to help it sustain B2B performance levels. The first is to penetrate new high growth areas such as B2B payments and emerging markets.

Its second key strategy is to expand its distribution footprint through its proprietary sales force and partner set. The third is to add new products and services through strategic investment and acquisitions.

In 2008 American Express invested in Concur and purchased the
GE Corporate Payment Services business. (see related article below)

Reblog this post [with Zemanta]

Mexico Expected to be a Major Growth Market for Corporate Cards
Commercial Payments International reports on the growth of Corporate Cards in Mexico:

Until recently corporate cards in Mexico were limited mainly to senior executives of very large companies. Several changes in this market have occurred recently indication that the Mexican corporate card market is poised for rapid growth:
  • Increasing numbers of mid-sized corporates and SMEs have begun to use some type of corporate payment cards
  • Petrol stations only recently began to accept cards for payment
  • The increased desire for visibility into corporate spend
  • The introduction of prepaid cards which have been successful as salary cards in a market with a large unbanked population.
Currently only four banks and American Express issue corporate cards in Mexico. In early 2008 Citibank, one of the leading global issuers of corporate cards, announced its plans to introduce new corporate card services in Mexico which will improve procurement process efficiency. Through its subsidiary Banamex, Citi already has over 150 corporate clients and have experienced a CAGR of 102% since 1999 indicating the significant opportunity in the market.
Reblog this post [with Zemanta]

Let's Get Those College Students a Wedgie!

Posted by John B. Frank Wednesday, September 17, 2008 0 comments

College Students Lead the Way Online
SEPTEMBER 17, 2008

Today's college students are digital natives—they have grown up with technology and Internet access at their fingertips. But what does that mean for the future? eMarketer estimates that this year 95.7% of college students—17.4 million strong—will go online at least once a month.

Note: (eMarketer defines a college student as anyone ages 18 or older who attends college full-time or part-time, including undergraduate, graduate-school and professional-school students.)

"College students are the most digitally connected demographic group in the US," says Debra Aho Williamson, senior analyst at eMarketer and author of the new report, College Students Online: Driving Change in Internet and Mobile Usage. "They have grown up with technology and it is a seamless part of their lives.Marketers looking for the next big trend online can learn a lot from college students.

"Students have played a prominent role in some of the biggest developments in the Internet and technology in recent years," says Ms. Williamson, "from social networking to the iPod."


In fact, entering college freshmen have already lived through a series of Internet-era milestones...often themselves created by college students:

  • 1990: The World Wide Web was born.
  • 1994: Two Stanford University students launched a site called "Yet Another Hierarchical Officious Oracle". It later became known by its acronym, Yahoo!. In the same year, the Mosaic Internet browser—precursor to Netscape—was created.
  • 1996: Two other Stanford students began collaborating on BackRub, which eventually became Google.
  • 1999: Northeastern University student Shawn Fanning created music file-sharing service Napster.
  • 2001: The first entry was posted to Wikipedia.
  • 2004: Harvard University student Mark Zuckerberg and a few classmates launched Facebook.
  • 2007: Apple introduced the iPhone.
"The college market is basically the testing ground for all technologies," Matt Britton, chief of brand development for youth marketing agency Mr. Youth tells eMarketer. "If it takes off there, it’s going to take off in the mass market."

"In addition, the college market is one of the most-attractive demographic groups for marketers because of students' discretionary budgets," says Ms. Williamson.|

According to a National Retail Federation (NRF) survey, conducted by BIGresearch, the back-to-college season alone is a huge purchasing occasion. Students and parents were expected to spend an estimated $11 billion on electronics in 2008.

"In so many areas, students are key drivers of change in technology usage," says Ms. Williamson. "They brought social networks into the mainstream, and such sites remain hugely popular with them."

Reblog this post [with Zemanta]

Wal-Mart files for Canadian banking license
Hollie Shaw , Canwest News Service

TORONTO - As worldwide markets plunge, Wal-Mart Canada is vowing to carry its low-cost credo into the financial sector.  The biggest mass merchant in Canada has applied for a banking license, joining the ranks of retailers such as Canadian Tire, Sears and Loblaw.

Two years after luring a former American Express Canada executive to head up its financial services department and expand into non-bank financial products, the retailer posted mandatory public notice on Saturday of its official bank application to the Office of the Superintendent of Financial Institutions.

'A license would allow us get into banking products and the obvious one would be a credit card, but if you look at other retailers the breadth of (potential) products is huge,' Wal-Mart spokesman Kevin Groh said.  "Services common to some other retailers (include) savings accounts, loans, mortgages, RSPs, GICs . . . but at this point it would be premature for us to speculate" the breadth of its offering, he said.

One thing seems certain - the price competition that Wal-Mart Canada has brought to the retail sector in the past decade, from Pampers to groceries, will likely be carried into the banking segment.  "Our approach in everything we have done to date is to be a price leader and eliminate costs that would pass on to customers," Groh said. 

Keith Howlett, retailing analyst at Desjardins Securities, said getting
into financial services is a valuable income stream for retailers.

"It is pretty lucrative for Loblaw and at Canadian Tire it was a big growth driver for them," he said. Credit cards are also a valuable source of information about its consumers, letting them see where and how they spend their money.

"I think Wal-Mart could have a huge opportunity there, and quite a different offering from ING or President's Choice Financial or Canadian Tire and something quite different from the banks. The traffic in their stores is enormous and is skewed to those least likely to get the value-added from banks," he said, noting that banks mostly try to court customers with high income or high savings.

"Wal-Mart could design a business model that goes against the grain." One such business, he suggested, would be to offer a lower-fee option on payday loans and services provided by companies such as Money Mart. "It's a huge, fast-growing business, it covers a huge number of people," but no banks or retailers are tapping into it.

Close to two years ago, Wal-Mart Canada signaled its interest in the banking business when it hired Trudy Fahie, former vice-president of financial services for American Express Canada, to take on the same role - a newly created position - at Wal-Mart Canada. Wal-Mart currently has ATMs and offers extended warranties, wire transfers and emergency bill payments through Western Union.

It's a different story in the United States, where the retailer has met with resistance to efforts to get into banking. Its applications for bank charters in Oklahoma and California were turned down and it ended up withdrawing an application in Utah.

Contactless and Clueless

Posted by John B. Frank 0 comments

Despite the fact that over 90% of Americans that own contactless payments cards like using them, three quarters of the population are not even aware of the technology's existence, according to a survey commissioned by the Smart Card Alliance.

Javelin Strategy and Research surveyed 500 contactless card users, finding that 92% think the technology is fast and easy to use. Respondents also use their cards regularly - with over 22% making payments with their contactless cards more than six times per month.

Contactless card users are also keen on mobile payments. The research found 43% are likely to use a handset as a mobile wallet, compared to just 19% of people who don't use contactless cards.

Nearly half - 47% - of contactless card owners would even switch carriers in order to make mobile payments.

The technology is rapidly gaining in popularity, with nine percent of the US population now possessing a contactless card. Last year the number of open network contactless cards in circulation reached 35 million, nearly double the 19 million in 2006.

Merchants are also adopting the technology, with an estimated 75,000, including taxi firms and transport operators as well as retailers, now accepting the cards.

"Contactless payment acceptance at merchants is taking off much faster than PIN debit did," says John Suchanec, SVP, payment research and innovations, Bank of America. "Contactless acceptance is already growing at a rate that it took seven years to achieve with PIN debit. Mobile will accelerate the curve."

But Javelin also questioned 1500 people representative of the US online population (not necessarily contactless card users) and found awareness of the technology is still poor.

Only a quarter of those surveyed are familiar with contactless, although this is up from 15% in 2006.
Reblog this post [with Zemanta]

More on More Card Skimming...

Posted by John B. Frank 0 comments

Tampa police show a skimming device — the false card slot goes over the original; underneath is a card reader that captures information. A camera is typically hidden on the ATM, often in a pamphlet holder, angled to view the monitor and keypad.

By KEITH MORELLI | The Tampa Tribune

A troubling trend in automated teller machinations has found its way into the Bay area and Tampa police say anyone who uses the convenient roadside bankers can be a potential victim.

Three times over the past two weeks, "skimmers" have been attached to automatic teller machines in the Bay area, devices that steal the numbers off debit and credit cards and record personal identification numbers as they are tapped into the keyboard.

Among the most recent victims: Tampa police Cpl. Mark Altimari, who put his debit card into the Bank of America ATM on the corner of Nebraska and Fowler avenues around lunchtime Sept. 5. He wanted to make a $20 withdrawal.

"I noticed my card wouldn't slide in smoothly," he said at a Monday news conference called to warn banking customers of the latest method of identity theft. "It kind of seemed odd to me." His card went in but only partially came out, he said. He pulled on it, and the whole card reader pulled off the face of the ATM. That's when he knew his card had been scanned by a device that was not an original part of the machine.

He immediately notified the Bank of America and bank security officials told him to check for a camera. He felt behind the trim over the keyboard and found a tiny camera the size of two sticks of gum hidden there. The entire piece of trim itself had been taped into place and looked like it was a part of the ATM. The camera, positioned over a tiny hole in the trim, was aimed at the keyboard to record PIN numbers as they are punched in.

Tampa police Sgt. Becky Bodamer said a similar card scanning device, this one less bulky and barely noticeable, was recovered at Pilot Bank, 4005 S. Dale Mabry Highway, around 4 p.m. Friday.

As of Monday morning, no one had reported missing any money from accounts in either of the banks, Bodamer said, but it was uncertain how many people had used the machines.

Some sophisticated devices are designed to transmit the card number the moment it is being used to criminals nearby, she said. But these devices were not that technologically advanced. They had to be gathered from the ATM and plugged into a computer to retrieve the data, she said. Because they were seized by police, it is assumed the thieves did not have a chance to obtain the information.

The two devices were different enough to lead detectives to think they likely were not put there by the same people, she said. Detectives are in contact with Clearwater investigators, who discovered a similar scanner at a bank there last week.

Clearwater police said that more than 20 people who used that Wachovia ATM over a two-day period last week have complained about money being pilfered from their accounts.

Officers found evidence of an adhesive on the ATM at the bank branch office at 2699 Gulf-to-Bay Blvd. They said the scanning device probably was attached to the machine and recorded information about customers' accounts, including personal identification numbers, as the customers used the machines.

In all cases, the devices looked like ordinary card slots, but were not. The false slot holds an additional card reader to capture information. Hidden cameras are one method of capturing a PIN, but another method is a false keyboard, glued onto the face of the ATM directly above the real keyboard. The fake records the PIN number as it is punched in.

If working properly, the machine will give the card back, along with any cash withdrawals, and the user would walk away not knowing their personal banking information had been compromised, Bodamer said.

In many instances, she said, the devices, "can't be detected unless you're a bank official."

Tampa police issued these tips for ATM safety:

  • Use secure ATM machines, inside a bank lobby or inside a store. Offenders can install the scanners quickly, but likely won't go inside a place of business to do it.
  • Cover the keyboard with your free hand when you punch in your PIN. This obstructs the view of any hidden cameras that may be present.
  • Skimming devices may protrude from the face of the ATM. If something looks suspicious or if the keyboard jiggles or the card slot is not quite level, leave and use another ATM and contact the bank to report it.
  • If the machine keeps your card, call the bank immediately.
  • Don't accept help from anyone hanging around the ATM. They may be there to try to observe your PIN number.

Bodamer said the ATM data-thieving trend began in South Florida and is making its way north. Those behind the high-tech identity thievery are likely part of an organized group with knowledge of how such instruments work, she said, and enough cash to invest in the equipment.


Reblog this post [with Zemanta]

New requirements for pre-authorized debits (PADs) mean changes for businesses using this payment option
OTTAWA, Sept. 16 /CNW Telbec/ - The Canadian Payments Association (CPA) has published new requirements for pre-authorized debits (PADs) to ensure appropriate information is disclosed to consumers and other parties using this option to pay for goods or services. As a result, all businesses using PADs to collect payments from their customers will need to make some changes to the forms or processes through which they obtain customers' authorization.

A PAD is a payment based on an agreement between a business and its customer through which the business obtains the customer's authorization to debit his or her bank account in accordance with specified terms. Requirements for these items to be processed through the clearing system are set out in the CPA's Rule H1 - Pre-authorized Debits. Recurring charges to credit cards are outside the scope of this framework.

On average, more than 2.3 million PADs were processed through the Canadian clearing system each business day during 2007.Mandatory Information Elements for Pre-authorized Debit Agreements

A key change in the new version of Rule H1 is the definition of mandatory elements to be included in the Payor's PAD Agreement - that is, the form or process through which the business or "payee" obtains the customer's authorization to debit his or her bank account. Among the mandatory elements are:

- information on how to cancel a PAD,
- the payee's contact information, and
- a standard statement with regard to the consumer's rights of recourse in the event of a debit that does not follow the terms of the agreement or is not authorized.

All payees using PADs must update their forms or electronic processes to reflect these new requirements by February 28, 2010. Each payee must submit a copy of its proposed forms and/or electronic processes to its financial institution to confirm that they meet the new requirements. Payor's PAD Agreements in effect before that date are grandfathered to avoid potential disruption to both consumers and payees. As part of the transition, CPA's member financial institutions will be updating their contractual arrangements with corporate clients on whose behalf they enter PADs into the clearing system to incorporate their clients' new obligations as PAD payees.

More Flexible Framework for Electronic PAD Agreements

The new framework also provides more flexibility to establish Payor's PAD Agreements through electronic means such as over the telephone or the internet. Payees who wish to initiate PAD Agreements electronically must submit their proposed electronic forms or processes to their financial
institution for review, including the proposed process to confirm the identity of the payor in the electronic environment. In addition, for all electronic Payor's PAD Agreements, the payee must send a written confirmation of all details to the payor in advance of the first PAD; the standard period is 15 days before the first PAD, which may be reduced by mutual agreement, but may not be waived

More information on the new requirements, including a copy of Rule H1, is available on the CPA's web site at www.cdnpay.ca.

The Canadian Payments Association (CPA), created by an Act of Parliament in 1980, operates Canada's national clearing and settlement systems; facilitates their interaction with other systems involved in the clearing and settlement of payments; and facilitates the development of new payment methods and technologies. It promotes the efficiency, safety and soundness of the clearing and settlement systems, taking into account the interests of users.Its current membership comprises virtually all of Canada's bank and non-bank deposit-taking financial institutions. In 2007, the CPA's systems cleared and settled transactions averaging $203 billion each business day.

For further information: Roger Dowdall, Vice-President, Communications and Education, Canadian Payments Association, (613) 238-4173, ext 3240
Reblog this post [with Zemanta]

41% of Online Shoppers Click "Bye" vs. "Buy"

Posted by John B. Frank Tuesday, September 16, 2008 0 comments

Here's a Press Release today from TeaLeaf.com regarding a survey done by them in conjunction with Harris Interactive. From a transactional perspective there seems to be a long way to go as 84% of those surveyed feel there's no reason an online transaction cannot be completed on the first try, but according to this poll, most sites are NOT meeting those expectations.

I say that's an easy fix and at the same time it would make the online experience as familiar and simple as the bricks and mortar experience. Here's how easy it would be to do.

Internet Retailers can provide "1 swipe shopping" by simply equipping their site's online shoppers with HomeATM's PIN Entry Device and get 'er dun right "the first time." An additional benefit to "reducing abandonment" is "reducing interchange fees."

It's easy to convince online shoppers to use a personal mag-stripe reader. By enhancing the security of the transaction you a "reducing the risk of fraud." By providing your loyal shoppers with a mini-swiper or a "Reducer"...Internet Retailers will get the added benefit of creating the very real perception that they are looking out for their customers well-being. Instead of giving away a free toaster for opening a savings account (circa 1965) they could give away a "free mini-swiper" for opening up a HATM PIN Debit Account.

The result is a true win-win situation...and according to this report, doing just that would be a "potential multi-billion dollar business opportunity"


Potential Multi-Billion Dollar Business Opportunity for Companies That Focus on Improving Online Customer Experiences


"Survey Says" 41% of Online Adults Click Away When They Encounter Problems, Many to a Competitor
  • For the fourth consecutive year, nearly 9 out of 10 (87%) online adults who have conducted an online transaction in the past year have experienced problems doing so;
  • 41% of online adults who experience problems transacting would switch to a competitor or abandon a transaction entirely if they experienced an online transaction problem;
  • Four in five online adults who experience problems (84%) share their experiences with others — both online and offline
Tealeaf®, the leader in online Customer Experience Management (CEM) software, today announced the results of the 4th annual survey of online consumer behavior. The study, commissioned by Tealeaf and conducted by Harris Interactive®, focused on consumer transactions on shopping, banking, travel and insurance websites. For the fourth year running, the survey revealed that nearly nine out of 10 (87%) consumers conducting transactions online have experienced problems. When online issues occur, there is an immediate business impact.

For example, if they experienced an online transaction issue, 41% of online adults who experience problems conducting online transactions would simply switch to an online or offline competitor or abandon a transaction entirely. This represents a $57 billion potential impact to revenue on shopping sites alone — a huge opportunity for companies to harness, by ensuring their websites work. On the Web, the competition is just a click away.

According to a recent Forrester Research, Inc. report, "Obstacles to Customer Experience Success, 2008," 91% of business decision-makers said customer experience is either very important or critical to their 2008 efforts. While customer experience is increasingly important to businesses, the Tealeaf survey conducted by Harris Interactive clearly highlights that companies need to take immediate steps to ensure they understand the experience of their customers who are transacting online.

While user expectations are high — more than four in five (84%) online adults feel there is no reason why an online transaction can't be completed on the first try — most sites are not meeting those expectations.

Preference for Online Channels is Rapidly Increasing, as are User Expectations
There is an increasing preference for conducting business online —
84% of all online adults have conducted an online transaction in the past year and more than one-third (35%) generally prefer to conduct business online, according to the survey. Further, 22% of online adults who have conducted an online transaction in the past year expect even better customer service online than when shopping in-person.

Poor Experiences Evoke Reactions
Online problems evoke strong emotions from consumers. According to the survey, the vast majority of online adults who experience problems when conducting online transactions (87%) feel frustrated when they experience such problems. Of those who experience problems, 41% reported feeling angry. Emotions can drive customers to take action by providing feedback via other channels.


Improve Customer Satisfaction and Retention

There is a lack of integration between the contact center and web channels of many businesses. The survey found that 47% of all online adults have contacted a company's call center after they encountered problems using the website. Among those, 64% did not feel that the service agent was knowledgeable about the website, and nearly two in five (38%) did not have their issue resolved. Results also show that, among online adults who have experienced poor customer service from a company's call center when calling about website issues, nearly three in four (72%) either stopped doing business with that company entirely (45%), decreased the amount of business they do with the company (37%), or lodged a complaint with the Better Business Bureau (13%). Improving the service centers' ability to support the online channel not only leads to increased customer satisfaction and retention, but can also turn a support call into an opportunity to expand the business relationship with that customer.

Customers Share Experiences, Amplifying Impacts

More than four in five (84%) online adults who experience problems conducting online transactions share their experiences with others, amplifying the impact of any single experience.


Among those who share their experiences with others, 82% do so using non-online modes of communication such as in-person (74%) and phone conversations (50%) with friends and family, while 58% use online channels to share complaints or reviews, such as on the company's website (39%), in an email to friends and family (23%), on a ratings and reviews website (16%), on an online message board (8%), or on a blog or social network (7%). These Internet postings and comments are often widely disseminated and long lived.


"At US Airways, we strive to do everything we can to be the airline of choice for our customers. To achieve this, we focus on reliability, convenience and appearance in all that we do. From achieving a first place ranking in on time performance among the ten largest U.S. carriers according to the Department of Transportation's Air Travel Consumer Report ... to providing a world-class website that provides our customers the quality service they deserve and demand," said Wes Graham, Director of Internet Distribution, US Airways. "We rely on Tealeaf for real visibility into our over one million customer sessions a day to help ensure we don't skip a beat in the online world. The Web is a major revenue channel for US Airways and extremely strategic to our overall business. With the Tealeaf dashboards we've created, I can see exactly how the site is performing now as compared to the previous week with just a quick glance."
"The Web has changed business; companies both large and small compete for the same customers. Now, competition is just a click away and customer expectations continue to grow," said Rebecca Ward, CEO of Tealeaf. "Businesses must take definitive steps to differentiate themselves by understanding and improving their customers' site experiences, and equipping their contact centers to truly meet the needs of online customers. Companies that do take action will be the ones to claim a greater share of this billion dollar business opportunity."

Survey Methodology -
The 2008 Online Transactions survey was conducted online by Harris Interactive on behalf of Tealeaf Technology, Inc. between August 5 and August 7, 2008 among 2,010 adults ages 18+, of whom, 1,798 have conducted an online transaction in the past year and 1,572 experienced problems when conducting online transactions. Data were weighted to be representative of the online U.S. adult population. For complete survey methodology, including weighting variables, please contact Shoshana Deutschkron at shoshanad@tealeaf.com.

Related articles by Zemanta
Reblog this post [with Zemanta]

Powered by Blogger.

Search This Blog

Our Manufacturing Facility

Learn More About Us

Find out how our patented technology can empower your financial institution.

Our secure two-factor online banking authentication eliminates dangerous passwords and usernames and replicates the same trusted process used to access cash at ATM's. (Insert Bank Issued Card, Enter Bank Issued PIN)

There is an R.O.I. as FI's also earn recurring revenue from each transaction conducted using our PCI 2.0 Certified PIN Entry Device. Our technology also provides a unique real-time P2P "Instant-Transfer" which allows your online banking customer to transfer cash from ANY of their bankcards to ANY other bankcard...with the Swipe of a card.

Help your bank eliminate phishing and your customers avoid identity theft by providing them with the ability to stop typing and start swiping. There is no safer way to conduct financial transactions online than by 3DES DUKPT encrypting the cardholder details, which we do at the mag-head "inside the box/outside the browser."

Total Pageviews

SLIM for PC or SmartPhone

SLIM for PC or SmartPhone
Click to Inquire

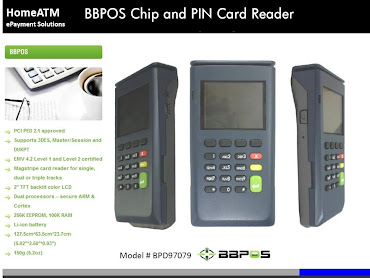
Chip and PIN eCommerce and Mobile

Chip and PIN eCommerce and Mobile
Click to Inquire

Kapersky Calls for Mass Adoption of Card Readers

Kapersky Calls for Mass Adoption of Card Readers

Translate This Blog

BobCaps

Search ePayment News (example: NFC)

About Me

My photo
Named one of the best Payment Industry News Blogs 4 Years Running

Feedjit

My Zimbio